Prepay Home Loan or Invest? Simple Math with Examples
Got a bonus or some savings and a home loan running? The question every borrower asks is whether to prepay the loan or invest the money. The answer comes down to a simple comparison, plus a few practical points.
What prepayment saves
Take a loan of ₹32 lakh at 9.25 percent with 18 years left. The EMI is about ₹30,000. If you prepay ₹3 lakh now and keep the same EMI, the loan ends years earlier and you save a large amount of interest over the remaining tenure. Adding even ₹3,000 a month to the EMI cuts it further. The exact figures depend on your balance, rate and months left; a calculator shows them in seconds.
The core comparison
Prepaying gives you a guaranteed return equal to your loan rate, in this case 9.25 percent, with no risk. Investing gives you an expected return that is not guaranteed and may be taxed. So the question is: can you reliably earn more than your loan rate after tax?
- Fixed deposits usually earn less than a home loan rate after tax, so prepaying usually wins against FDs.
- Equity investments may earn more over long periods but can fall, and the gain is taxed.
Points that change the answer
- Emergency fund first. Never prepay with money you may need in the next six months.
- Tax benefits. Depending on the tax regime you choose, home loan interest and principal may give deductions. Prepaying can reduce the interest you claim.
- Early years matter most. Interest is front-loaded; a prepayment in the first years of a loan saves much more than one near the end.
- Peace of mind. Many families value being debt-free earlier, which no spreadsheet captures.
Reduce EMI or tenure?
After a prepayment, banks usually keep the EMI and shorten the tenure. This saves the most interest. Reducing the EMI instead helps if your monthly budget is tight.
What about a balance transfer?
If another bank offers a lower rate, compare the saving with all transfer charges: processing fee, legal and valuation fees and stamp duty. First ask your own bank to reset your rate; many do for a small fee.
Work out your own numbers
Our Home Loan Prepayment & Balance Transfer Calculator shows the interest and months saved for a lump sum and an extra monthly payment, and the net saving from a transfer after charges, from your own loan statement.
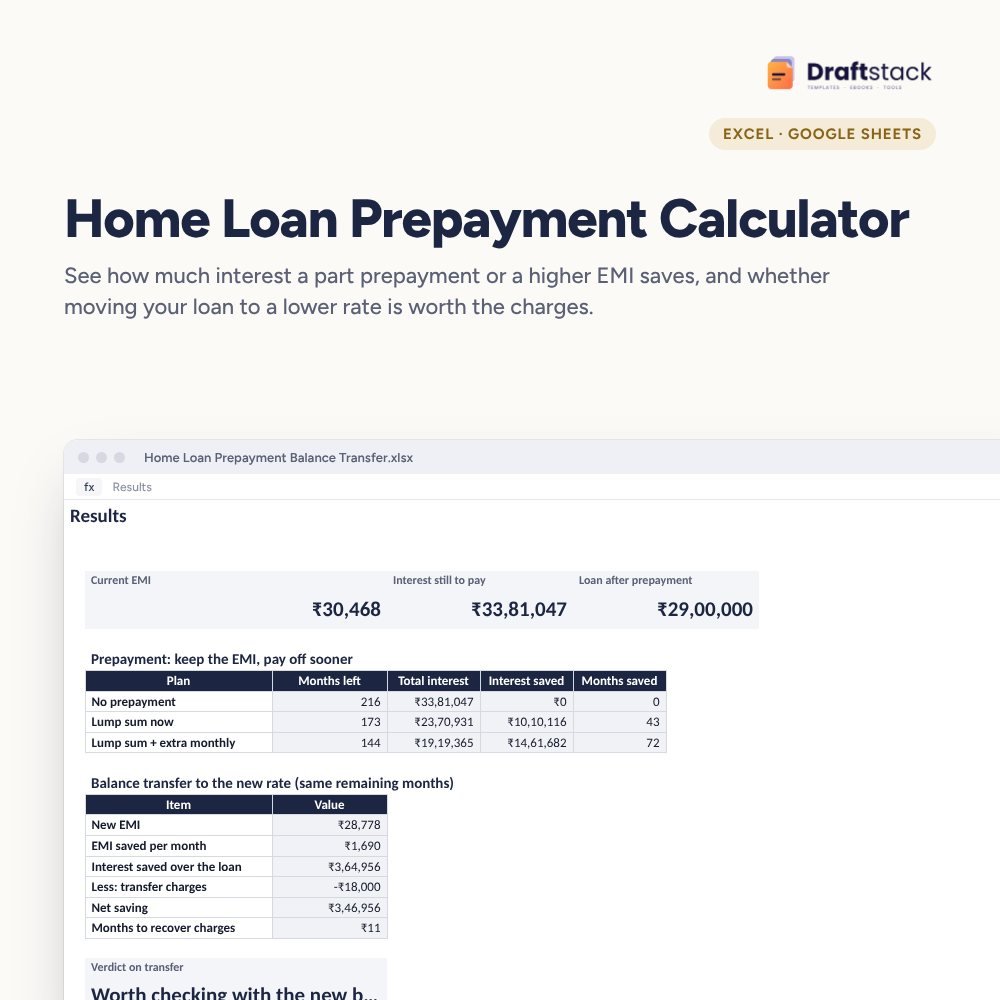 The template from this guideHome Loan Prepayment & Balance Transfer Calculator (Excel)
₹112
 WhatsApp
Free Monthly Budget Sheet
A printable one-page budget sheet: income, fixed bills, daily spending and savings for the month. Print it or fill it on your phone.
More guides
How to Write a Business Plan for a Small Business in India
How to write a business plan for a shop or small business in India: the nine sections, estimating sales and costs, and finding your break-even month.
NIELIT CCC Exam: Syllabus, Pattern and How to Prepare
CCC (Course on Computer Concepts) is a basic computer literacy certificate run by NIELIT, a body under the Government of India. Many state and central governmen
BOQ for Civil Work: What It Is and How to Prepare It
What a bill of quantities is, how to prepare a BOQ for civil work with units and rates, and how it becomes running bills during construction.